
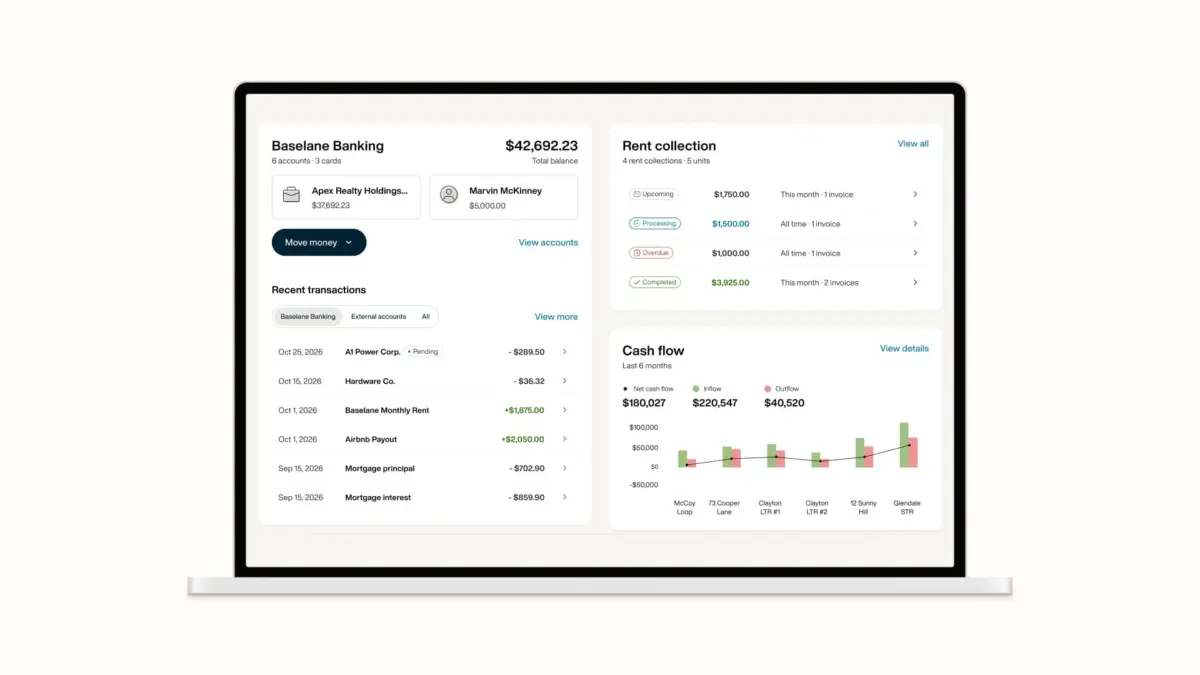
Managing rental properties across multiple limited liability companies, tracking income and expenses down to the individual property level, and keeping security deposits rigorously organized has long required more than a standard business checking account. Today’s real estate investors and portfolio operators need banking tools engineered specifically for the operational complexities of multi-property management. Choosing the right financial solution can dramatically streamline day-to-day operations, organize cash flow across various entities, and seamlessly connect core banking activities with broader bookkeeping and tax reporting workflows.
Whether an operator manages a single residential rental or oversees a vast portfolio spanning dozens of properties across different geographic regions, selecting a banking platform that thoroughly understands real estate investing is critical for long-term growth. Traditional small business banking models often fall short when applied to the unique demands of property ownership. Unlike a traditional retail business that operates out of a single storefront with one primary checking account, a real estate investor managing multiple assets through various LLCs faces a distinct administrative burden. Juggling separate bank logins and multiple disconnected financial applications frequently spreads vital data across disparate systems, making monthly reconciliation and annual tax preparation intensely time-consuming.
To address these challenges, the financial technology landscape has expanded to include a diverse array of specialized digital platforms, tech-forward neo-banks, and traditional institutions offering commercial real estate lending. Among the digital-first solutions designed specifically for property investors, Baselane has emerged as a prominent platform combining property-level banking accounts with automated bookkeeping and rent collection. By allowing investors to open unlimited checking and savings accounts organized strictly by property, entity, or operational purpose within a single dashboard, the platform tackles the core operational challenge of maintaining cash flow visibility without manual spreadsheet tracking. Furthermore, such systems automatically assign incoming and outgoing transactions to the correct property, entity, and tax category utilizing an extensive index of real estate-specific categories, thereby easing the year-end tax reporting burden.
While digital platforms focus heavily on workflow automation and property-level organization, other financial providers cater to different facets of real estate investment and management. Stessa, based in Oakland, California, operates primarily as a property management and portfolio tracking tool that incorporates cash management accounts. This setup enables investors to separate funds by property or portfolio while keeping cash flow directly tied to leasing, maintenance tracking, and portfolio performance metrics. Similarly, online platforms like Bluevine offer small business banking features paired with working capital products, allowing operators to access business lines of credit for property repairs or capital improvements, though they typically require external software for comprehensive property-level bookkeeping and Schedule E reporting.
For investors who prioritize traditional banking relationships, physical branch access, and large-scale commercial lending, major institutions such as Chase and Wells Fargo remain prominent fixtures. Chase offers an extensive nationwide network of branches tailored for investors who regularly handle physical cash deposits, require merchant services, or prefer traditional commercial banking relationships. Wells Fargo, meanwhile, provides specialized multifamily lending capabilities, catering primarily to experienced developers and institutional investors seeking agency financing programs through Fannie Mae, Freddie Mac, or the Federal Housing Administration. U.S. Bank occupies a similar traditional space, offering direct investment property loans across various asset classes—including multifamily, office, warehouse, and retail spaces—alongside fee-free business checking options for established operators seeking branch access without fintech complexity.
Other digital and online banks have carved out niches by targeting specific operational models. Live Oak Bank has established itself as a national leader in SBA 7(a) financing, providing a streamlined digital process for investors seeking government-backed loans for eligible business acquisitions or major renovations, keeping in mind that these loan programs generally cannot fund rental properties that the borrower does not occupy. Mercury targets tech-forward holding company structures with robust application programming interface access for custom financial automation, though it operates without FDIC insurance. Axos Bank provides digital-only lending solutions entirely online, appealing to investors pursuing debt service coverage ratio financing strategies. Meanwhile, Relay focuses heavily on multi-account cash flow management and team collaboration, supporting numerous checking accounts and percentage-based automated transfers aligned with specific cash flow allocation strategies, albeit requiring paid subscriptions for advanced features and higher account limits.
Despite the variety of options available across the financial sector, specialized platforms continue to distinguish themselves by directly resolving the friction points inherent in property management. Traditional banks were fundamentally built to serve general commercial enterprises rather than the intricate, multi-entity structures required by modern rental property owners. By integrating dedicated security deposit accounts, automated expense categorization, and tools tailored for short-term rental operators—such as virtual debit cards with strict spending limits assigned to property co-hosts or maintenance crews—these specialized banking solutions bridge the historical gap between day-to-day financial transactions and specialized real estate accounting needs. As the real estate sector continues to evolve, the integration of banking, bookkeeping, and tax preparation workflows remains a central consideration for operators seeking to scale their portfolios efficiently.