
The stock market has once again proved its capacity to surprise, leaving investors grappling with a familiar emotional cycle. As valuations climb to historic heights, driven largely by a frenzied boom in Artificial Intelligence, a sense of anxiety has taken hold across financial circles. Market participants are increasingly asking whether this latest technological surge is merely a precursor to an unprecedented economic crash, echoing the fears that surrounded earlier market manias.
For those who have managed to tune out the daily market drama, the current landscape centers on the rapid rise of Artificial Intelligence, massive capital deployment by major technology firms, and soaring valuations across the sector. Yet, this rapid ascent has triggered deep-seated anxieties among investors who worry that the current mania is moving too fast and too intensely. Many fear that the world is heading toward a magnified version of the early 2000s dot-com crash—a historical parallel that carries personal resonance for veterans of the tech industry who navigated the turbulence of that era.

Will the AI Bubble Ruin Our Retirement?
Addressing these concerns requires looking at how financial anxiety evolves over time. Reflecting on decades of market participation reveals a consistent pattern in human worry. More than twenty years ago, during the mid-2000s, investors faced an entirely different set of perceived existential threats. Back then, public discourse was dominated by fears of geopolitical instability, soaring national debt, and persistent inflation. The overarching market worry at the time was not an artificial intelligence bubble, but rather a dangerously overvalued housing market, alongside anxieties regarding the outsourcing of domestic jobs to overseas markets like India and China. There was even widespread debate over "Peak Oil," with many convinced that skyrocketing fossil fuel consumption would inevitably outstrip supply and cripple the global economy.
Despite those intense anxieties, the subsequent two decades demonstrated the resilience of the global economy. Even the Great Financial Crisis—triggered by housing market irrational exuberance and excessive financial leverage—pales in the rearview mirror when viewed through the lens of long-term market performance. A substantial investment made during those volatile years still managed to grow significantly over the long term, absorbing subsequent market shocks, including the pandemic-induced downturn of 2020.

Simultaneously, the broader world made remarkable strides that defied the pessimistic forecasts of the mid-2000s. Global extreme poverty rates dropped substantially, infant mortality was cut in half, and clean energy alternatives emerged as a dominant force. Solar power generation expanded dramatically as panel costs plummeted, while electric vehicle adoption surged from near-zero to a substantial share of worldwide automotive sales. History suggests that focusing energy on an uncertain and frightening future is rarely as productive as maintaining a long-term perspective.
Prosperity Comes From Productivity
The central question facing modern investors is whether the current environment is fundamentally different. Skeptics point to the massive U.S. national debt, the unprecedented scale of the AI boom, and speculative existential risks as reasons why the market might not recover from the next inevitable correction. Financial media outlets frequently amplify these narratives, capitalizing on negative sentiment.

However, these pessimistic perspectives often overlook a foundational economic truth: true societal prosperity is not derived from the financial system or abstract stock market tickers, which are ultimately human constructs represented by numbers on digital screens. Instead, prosperity stems directly from productivity.
The underlying architecture of capitalism is inherently choppy and prone to wild sentiment swings. Beneath the surface turbulence, however, real people continue to perform tangible work and develop genuine innovations. If a financial system experiences a systemic failure due to speculative excess, history shows that societies possess the capacity to restructure financial metrics and resume productive activity. The standard of living, economic growth, and the feasibility of long-term financial independence are anchored entirely in high productivity and technological capability.

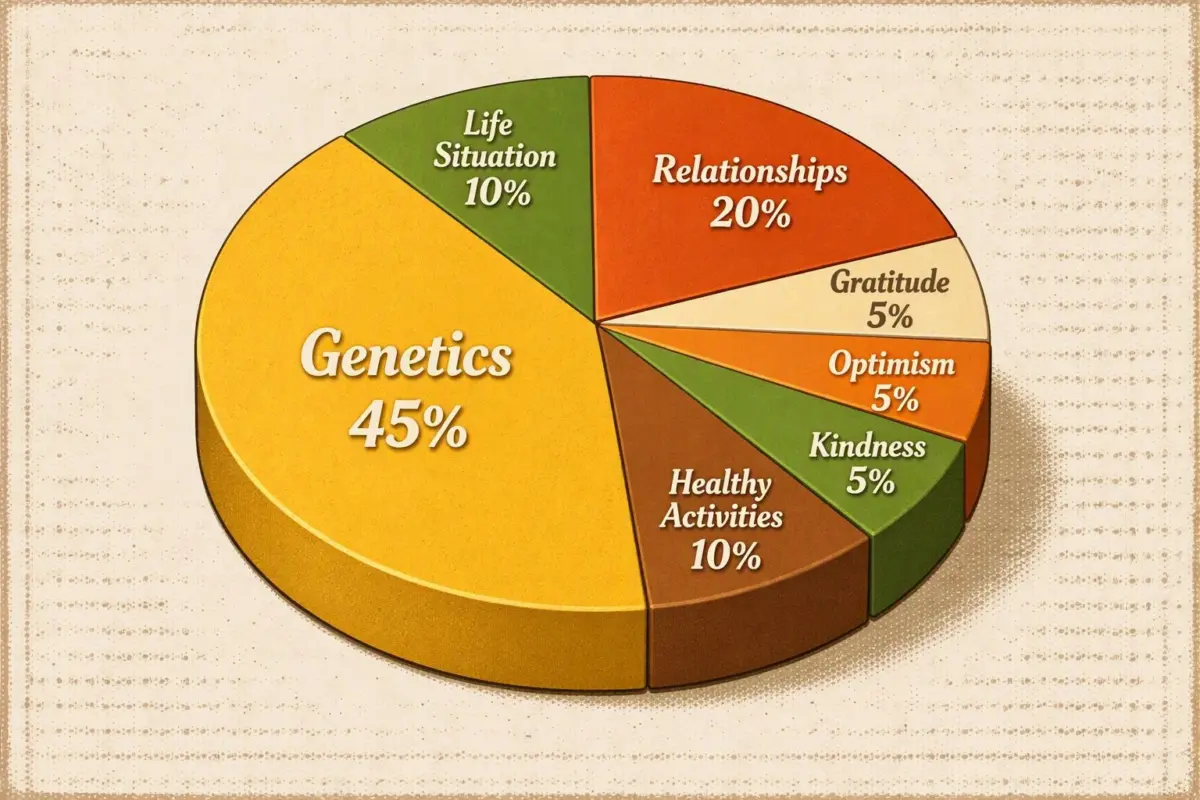
Once a society achieves a certain baseline standard of living, human happiness tends to decouple from pure wealth accumulation. First-world populations surpassed those minimum material requirements decades ago, shifting the focus of well-being toward non-financial factors. Psychological research suggests that long-term happiness is driven heavily by personal relationships, a lifelong philosophy of gratitude and optimism, and engagement in healthy physical activities.
Understanding and Combating Fear
The persistence of financial anxiety, even among those who have successfully achieved long-term financial security, points to a deeper psychological mechanism. Human beings evolved primarily as danger-detection machines. This background fear served as an evolutionary survival trait, protecting early humans from immediate physical threats.

The challenge of modern life is that once immediate physical dangers like predators, disease, and starvation are mitigated, the human brain continues to search for new subjects of worry. As basic survival needs are met, anxieties shift toward social acceptance, financial comparisons, and ultimately, high-level administrative concerns such as tax minimization strategies and government-mandated withdrawal rules.
Overcoming this pervasive background fear requires self-awareness and rational analysis. The first step involves examining one’s personal history and recognizing how childhood experiences or familial scarcity mindsets influence present-day attitudes toward money. Individuals who grew up during periods of economic hardship or personal trauma frequently carry residual anxiety into adulthood, projecting historical scarcity onto a secure present.

Identifying the specific nature of a fear—such as mapping out the realistic worst-case scenario of running out of financial resources—often reveals that the feared outcome is far less catastrophic than imagined. Taking deliberate action serves as an effective antidote to fear, transforming the unfamiliar into the manageable and building personal resilience.
Furthermore, curating one’s mental diet by reducing consumption of sensationalized daily news helps mitigate unnecessary panic. Human beings are biologically wired to solve problems through physical and mental action in real-world environments, rather than through passive digital consumption. Engaging in regular learning, physical movement, and surrounding oneself with optimistic, productive peers helps realign daily life with natural human functioning.

Navigating the AI Era as an Experiment
Approaching major technological shifts through the framework of experimentation can fundamentally alter how individuals perceive uncertainty. Whether applied to personal decisions or macroeconomic trends, viewing change as an experiment neutralizes panic and replaces it with intellectual curiosity.
The current Artificial Intelligence boom can be productively viewed through this experimental lens. Rather than succumbing to doom-scrolling and apprehension, understanding the underlying mechanics of AI reveals its primary economic function: a powerful cognitive tool designed to enhance human efficiency.

Much like previous technological revolutions, AI increases productivity and drives economic prosperity by lowering the cost of complex cognitive tasks. At the same time, it introduces labor market disruptions, displacing entry-level office roles and eventually transforming transportation and logistics sectors. Historically, such technological leaps simultaneously drive down the cost of essential services and catalyze the creation of entirely new industries, mirroring the transformative impact of the internet and mobile computing.
The economic rewards of these innovations naturally tend to favor those who own the underlying platforms and capital assets, benefiting both institutional shareholders and retail investors alike. Ultimately, Artificial Intelligence represents another technological milestone offering individuals a choice: view the unknown through the lens of fear, or utilize it as a catalyst for ongoing education, adaptability, and engagement in a rapidly evolving world.