
Insurance is built on a fundamental social contract. When homeowners sign a policy with a provider like State Farm or Allstate, they are affirming their membership in a broader community. Their monthly or annual payments go toward repairing another person’s burned or flooded home, and in return, that shared pool of capital will support them if disaster strikes. Society permits private insurance companies to sell policies on an open market, while electing and appointing public officials to oversee that system and safeguard the interests of everyday homeowners.
That is how the arrangement is designed to work, but it was not how reality played out for Lynn McIntyre.
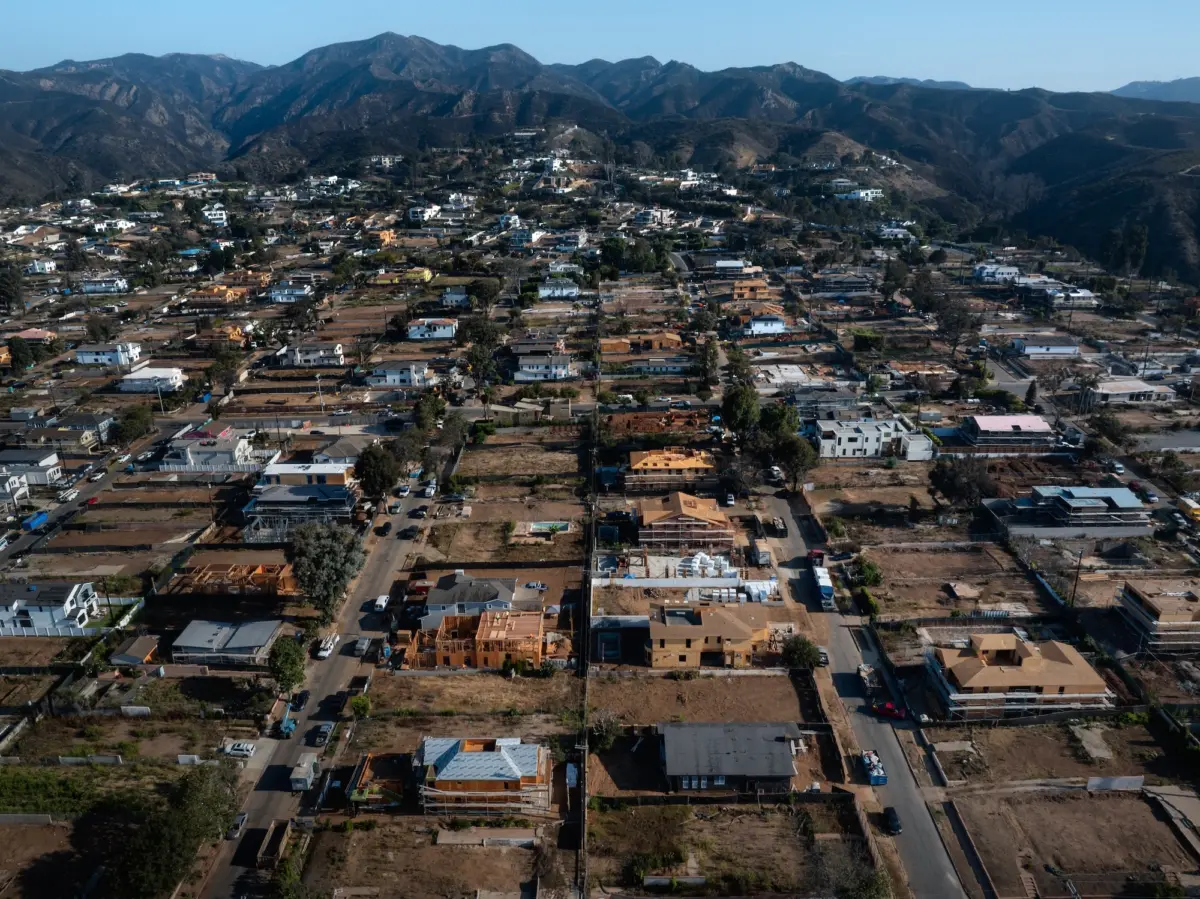
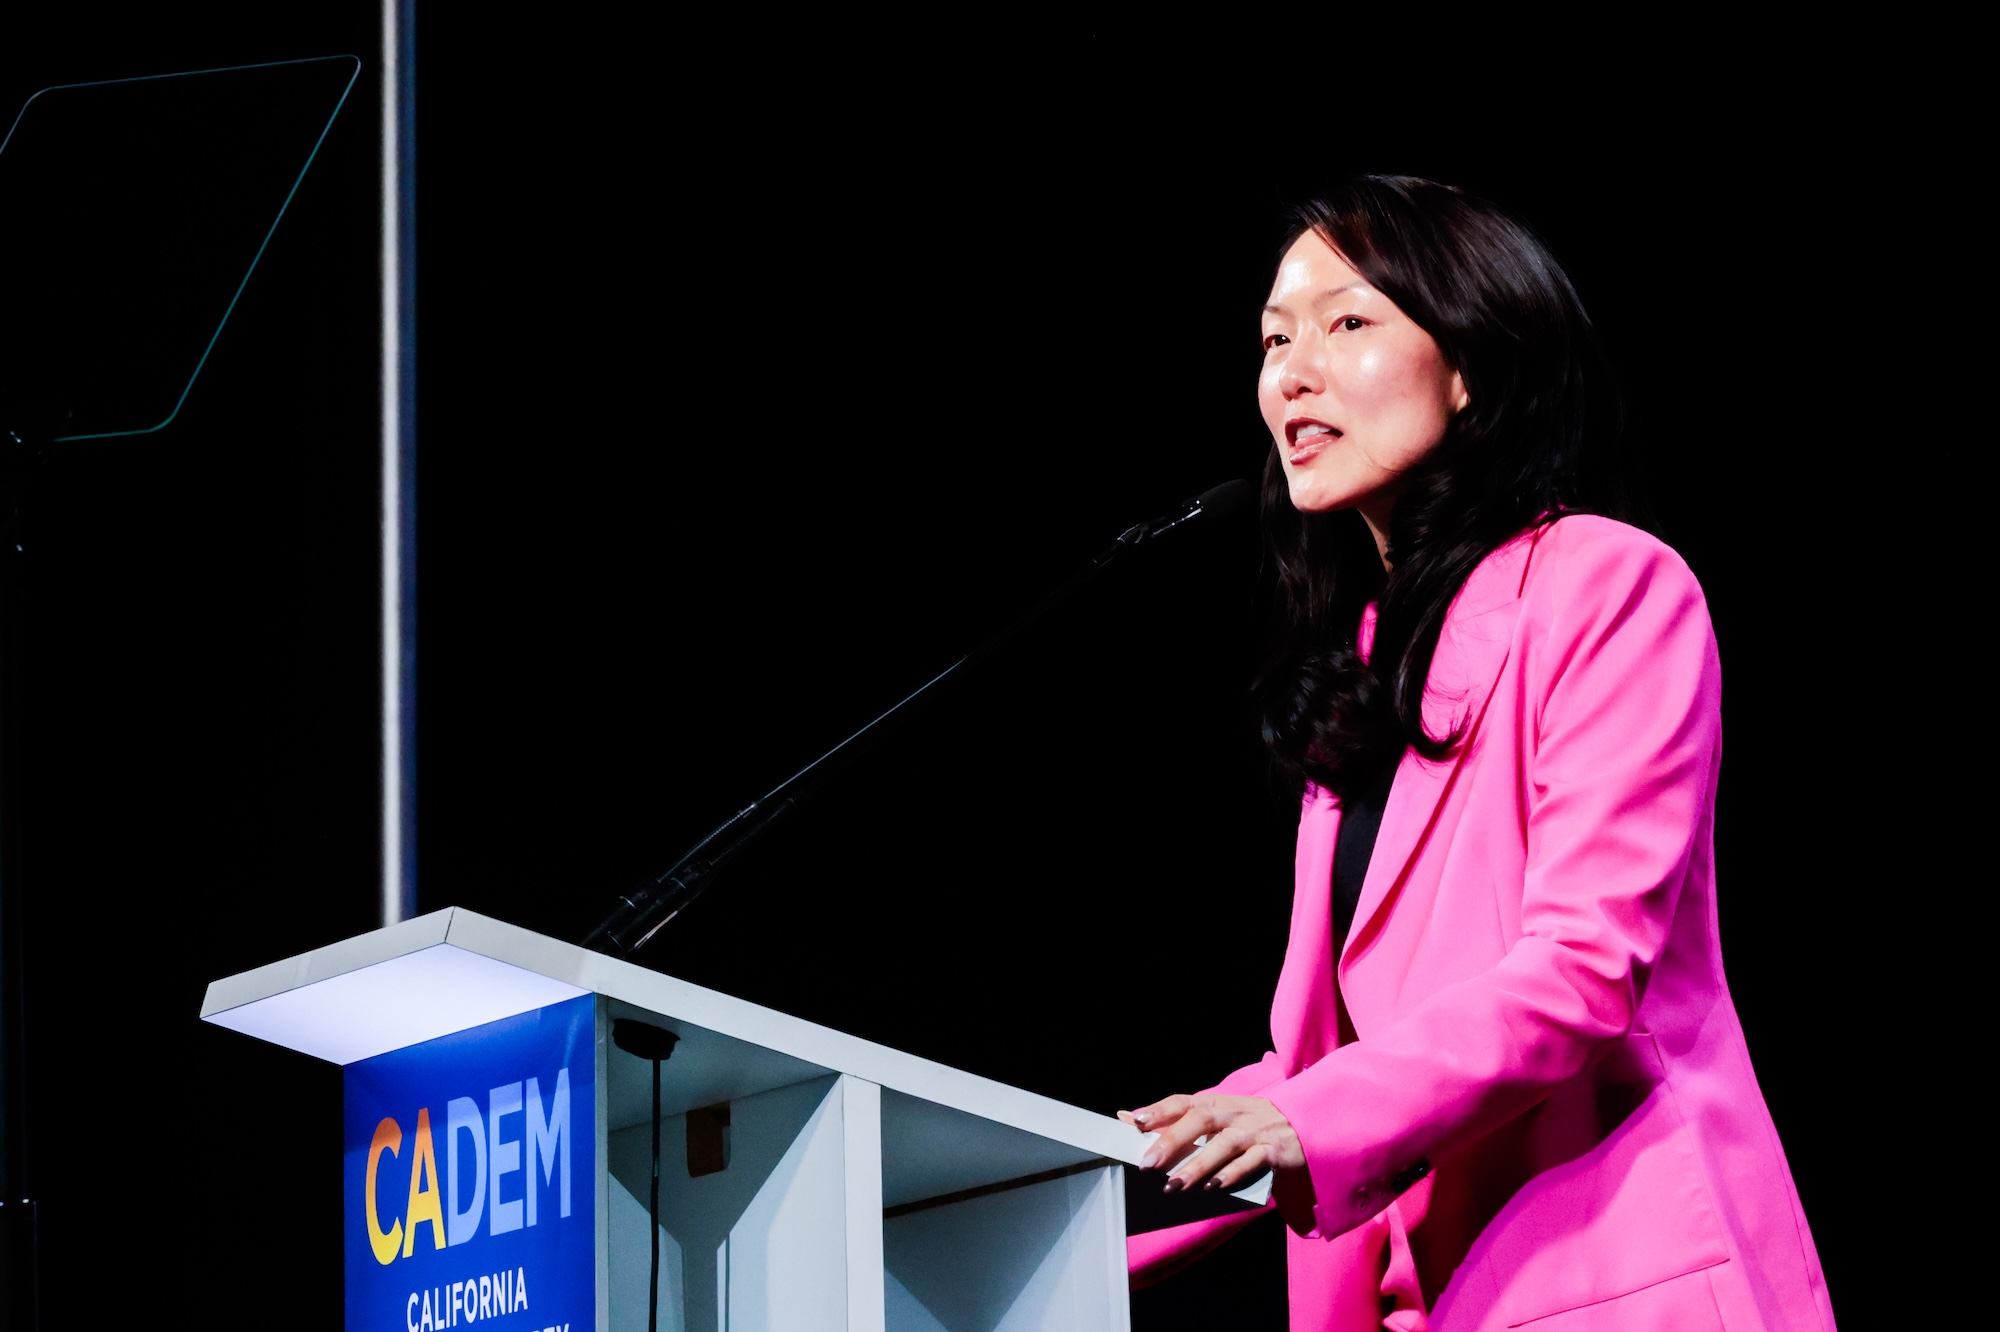
When McIntyre’s mother passed away in 2022, she inherited her longtime home in the "Alphabets," a picturesque neighborhood tucked close to the coast in western Los Angeles. McIntyre and her daughter had lived in the residence for just a single year when their private insurer, Liberty Mutual, dropped their fire coverage entirely. Unable to find another private company willing to shoulder the home’s wildfire risk, McIntyre was forced to enroll in the California FAIR Plan—the state-backed "insurer of last resort." The enrollment added an extra $5,000 a year to her expenses, layered on top of her regular homeowners insurance premiums with Liberty.
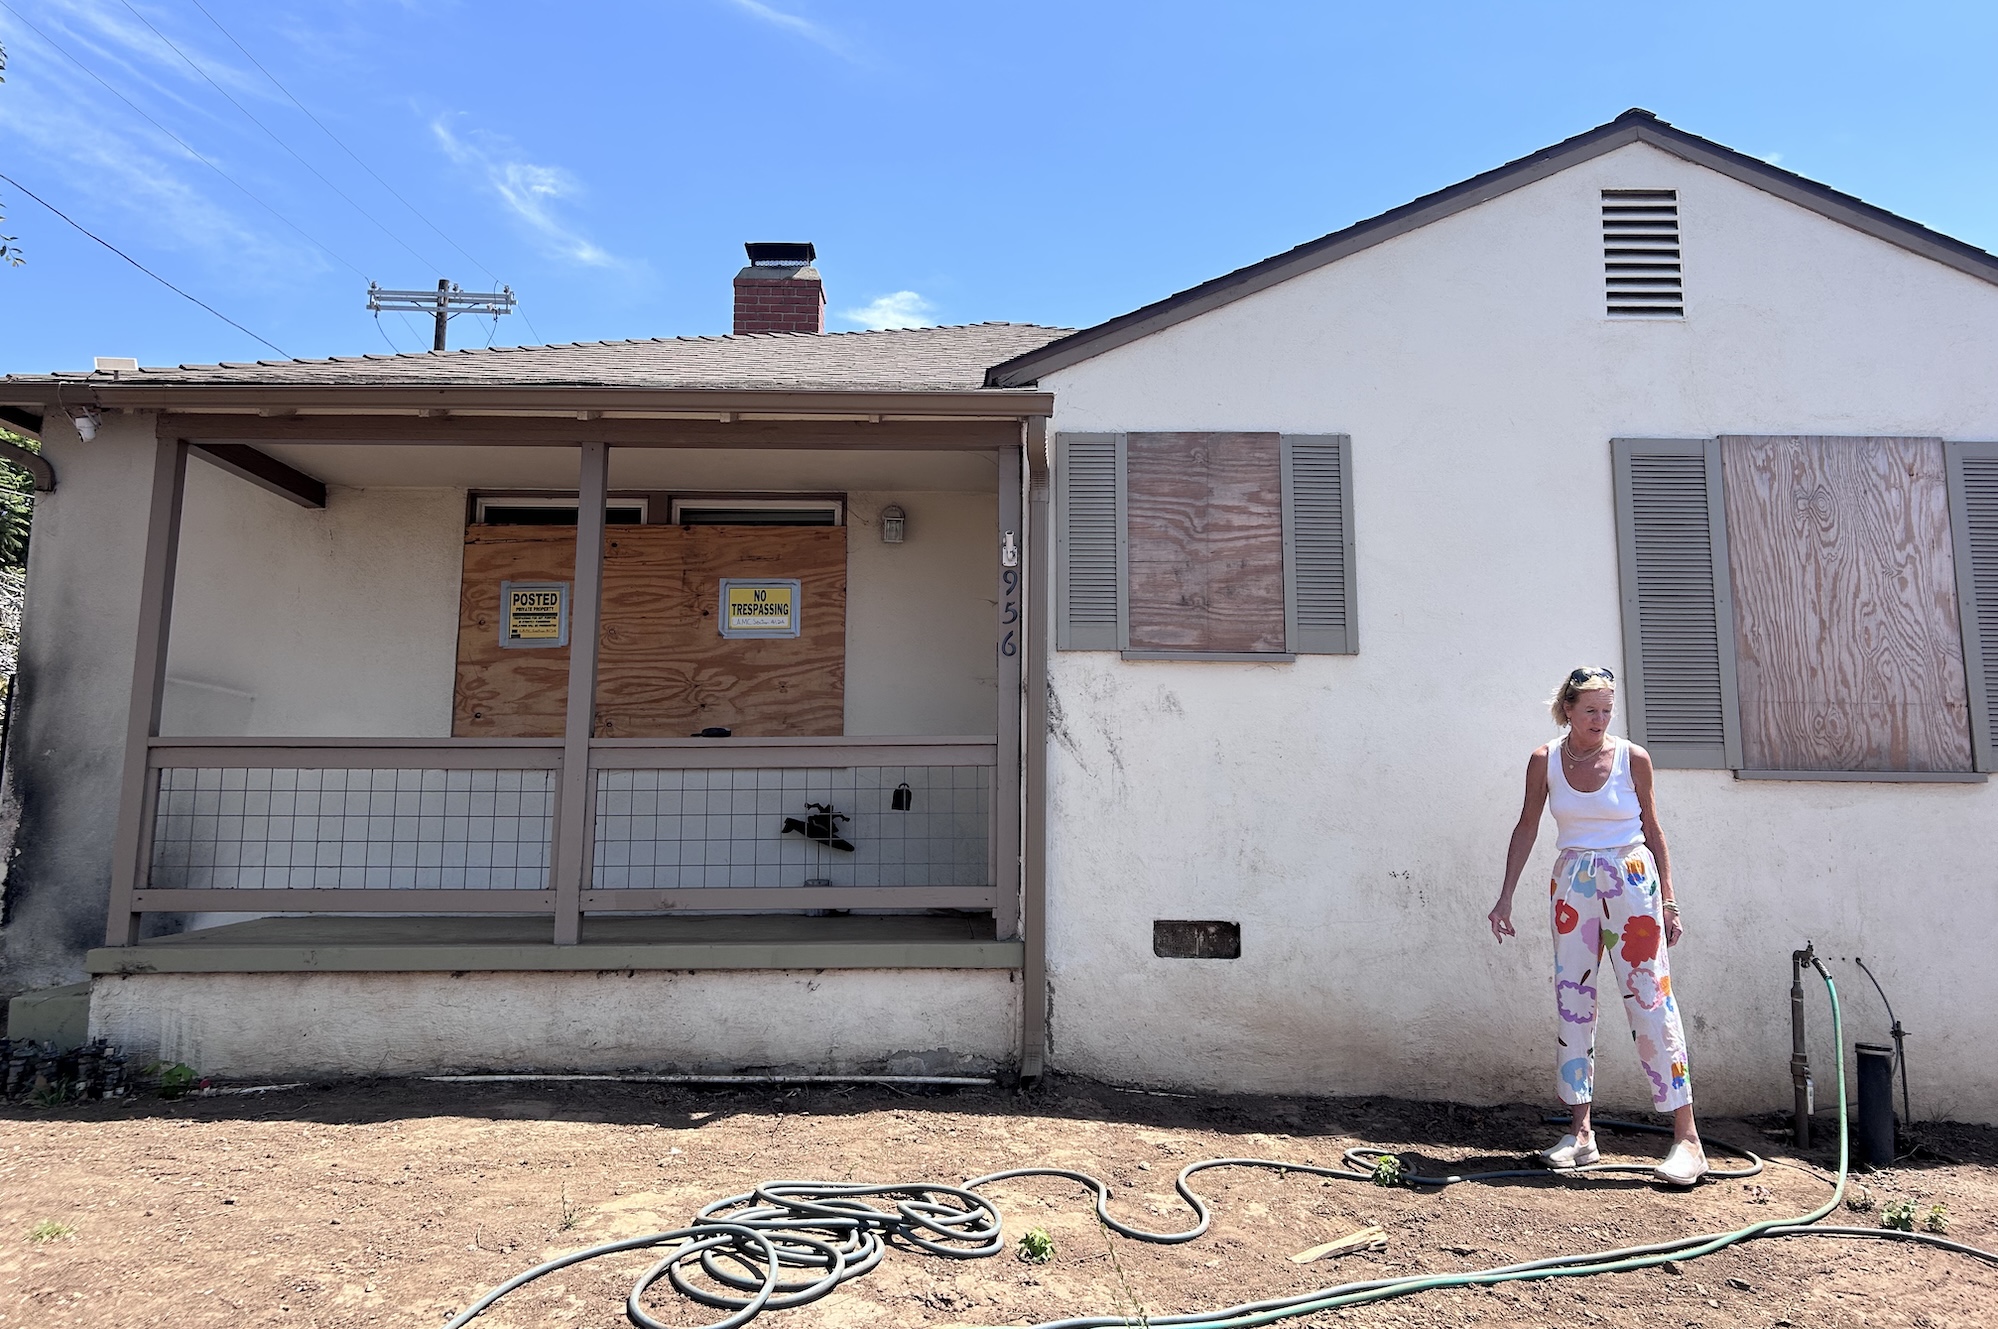
When the Palisades Fire tore through the Alphabet Streets in early 2025, McIntyre’s modest bungalow miraculously remained standing. However, the interior was heavily fouled by thick smoke and ash that had poured in through the windows and ventilation systems, leaving her belongings stained and ruined beyond recognition. When she filed a formal claim with the FAIR Plan, company adjusters informed her that she was essentially out of luck. They agreed to cover the cost of a temporary apartment, but offered virtually nothing else to aid in the recovery.
McIntyre, who spent years working as a real estate broker, plunged into months of grueling administrative warfare, battling 10 different adjusters and dozens of representatives from the FAIR Plan. Her efforts yielded nothing. Employees turned her away at every turn, hiring independent third-party adjusters proved completely ineffective, and even her attorney expressed shock at the FAIR Plan’s unyielding obstruction. While most of her neighbors cleared away charred debris and began constructing modern, fire-resilient homes—often much larger than the properties they lost—McIntyre’s old bungalow remained sitting vacant, coated in residual smoke.
It was not until late August, more than a year and a half after the wildfire, that she was finally able to begin repairs. The work was not funded by insurance payouts, but by a nearly $200,000 federal loan that she will eventually have to repay. Compounding her frustration, the FAIR Plan attempted to cut off her temporary housing allowances, arguing that power and water had been restored to her neighborhood and demanding that she move back home—ignoring the reality that her house still featured boarded-up windows and a scorched exterior. Meanwhile, Liberty Mutual delivered a fresh blow over the summer, informing her that they were canceling her non-fire coverage as well.
"The next time a fire comes through, I’m just going to light it on fire, because I’m not going to go through this again," McIntyre said wryly while standing in her doorway, the noise of construction equipment rattling from neighboring rebuilds.
Ensuring that Californians like McIntyre have access to viable, affordable insurance falls to an elected official whom many residents have likely never heard of: the state insurance commissioner. This official is one of only eight statewide elected positions in California, holding broad regulatory power over the companies that provide fire, home, and auto coverage across the Golden State.
Over the preceding eight years, the incumbent commissioner presided over what stakeholders across the political spectrum have increasingly characterized as a disaster, a crisis, and a full-scale collapse of the property insurance market. Now, as the current commissioner terms out of office, two prominent Democratic candidates—State Senator Ben Allen and former San Francisco supervisor and organizer Jane Kim—have emerged, each promising to fix the broken system. Their candidacies highlight a deeper ideological debate within the Democratic Party over how society should adapt to accelerating climate change. Allen, an established legislator representing Pacific Palisades, advocates for repairing and stabilizing the private market, whereas Kim, a left-wing organizer, argues for abandoning the private market model entirely in favor of a public alternative.
Whoever wins the upcoming election will inherit an insurance system severely battered by a decade of catastrophic wildfires, widespread policy cancellations by fleeing insurers, and compounding economic turbulence. Decades of aggressive forest management failures combined with worsening climate change have transformed California’s vast woodlands into volatile tinderboxes, a trend that experts warn will only intensify as global temperatures rise.
The current crisis traces its immediate roots to a sequence of unprecedented wildfires that struck between 2015 and 2020. Those infernos scorched roughly 4 million acres of land and destroyed 35,000 homes, frequently consuming regions that historically had no record of burning. Major private insurers like State Farm and Farmers were forced to disburse billions of dollars in claims—wiping out the entirety of the profits they had accumulated from writing fire policies over the prior two decades.
Insurers argued that they were charging premiums far too low to sustain such massive losses, but the price of insurance cannot adjust as quickly or elastically as commodities like gasoline or paper towels. Insurance providers are legally required to secure formal approval from the state insurance commissioner before implementing rate hikes. California maintained strict oversight over those rate requests, repeatedly blocking companies from passing the financial burden of post-fire payouts directly onto local homeowners. The industry’s retaliatory response was to scale back operations across California, dropping tens of thousands of existing policyholders and announcing plans to phase out or completely halt the issuance of new policies.
"There’s something broken that so many of us are facing the same issues, and they just think they can just roughshod right on over all of us," McIntyre said.
The widespread unavailability of coverage is now rippling outward, actively damaging the state’s broader economy. Approximately one in seven California realtors reported having a home sale fall through in 2024 due to insurance complications, the state-backed FAIR Plan exhausted its available claims capital, and average statewide premiums rose significantly. This squeeze is steadily bleeding out of the most flammable foothill zones, creating severe coverage hurdles for homeowners residing in traditionally low-risk areas as well.
The outcome of the election carries profound implications for the insurance bills of millions of residents and will dictate the long-term viability of fire-prone communities throughout the state. More broadly, the race serves as a bellwether for how American voters wish to approach the complex, expensive challenge of adapting to a warming planet. Whoever secures victory will be tasked with translating a voter mandate into immediate, short-term relief—a formidable undertaking under any circumstances, let alone amid an unfolding structural collapse.
The Roots of a Two-Tiered Market
The current insurance emergency is thoroughly modern in its symptoms, but its foundations stretch back a century. Over the past several decades, California permitted the construction of millions of homes within the "wildland-urban interface"—the highly flammable zones sprawling immediately outside major urban centers. Developers rushed into the mountains surrounding Lake Tahoe and the desert hills east of San Diego, frequently building without adequate fire mitigation measures. Many of these subdivisions featured wooden siding, flammable fencing, and densely packed lots. These are precisely the communities that have been ravaged by recent wildfires, and consequently, the exact areas that private insurers are now abandoning en masse.
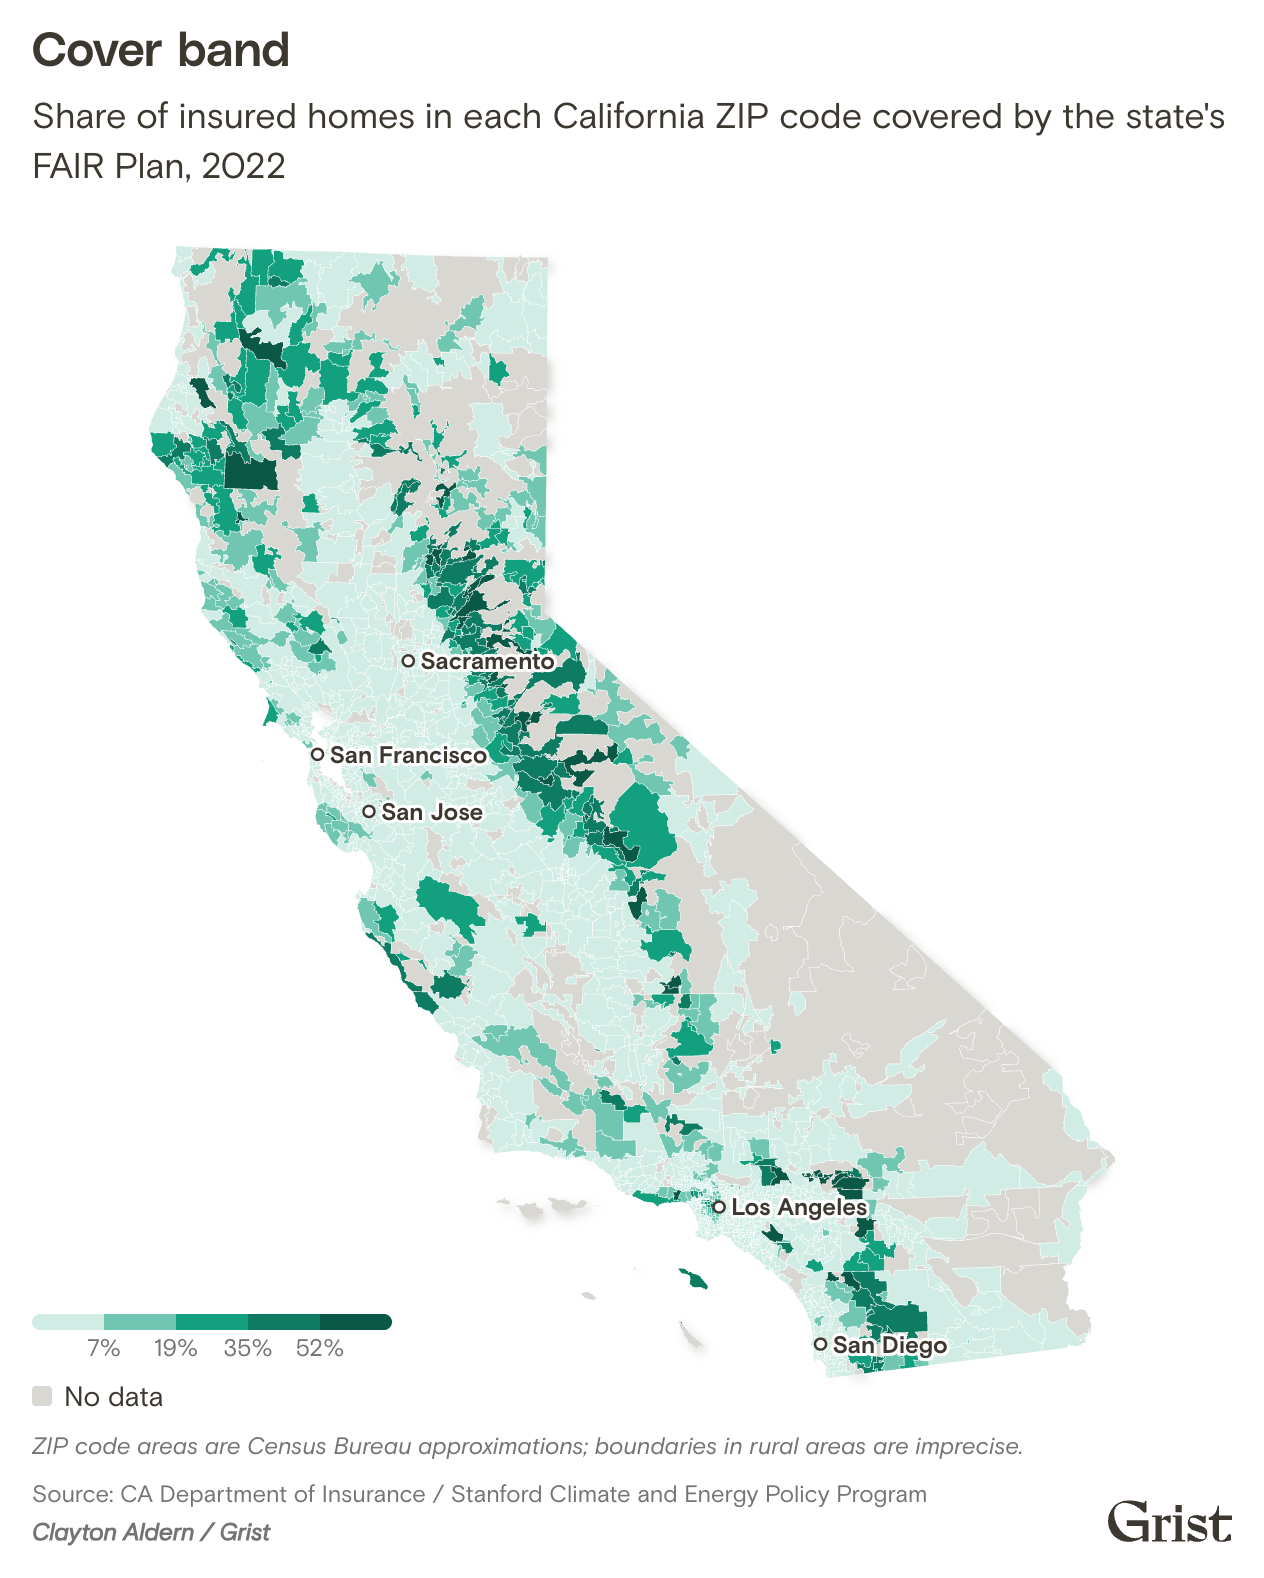
This history of high-risk real estate development has fostered an unusual economic reality that insurance scholar Carolyn Kousky has characterized as "a tale of two markets." While insurance rates ticked up incrementally in naturally wetter regions like San Francisco or low-lying Fresno, the market went entirely haywire in fire-prone areas such as Malibu and the High Sierra. Nearly half of all households located in high-fire-risk zones lost their private coverage between 2018 and 2024.
Originally established to serve as a narrow fringe safety net, the California FAIR Plan rapidly swelled into the primary option for thousands of stranded property owners. Since 2018, its market share in high-risk regions has ballooned from under 1 percent to 5 percent statewide, reaching upwards of 80 percent in specific vulnerable communities.
In theory, California voters wield significant democratic oversight over this volatile market. While every U.S. state features an insurance commissioner, California is one of roughly a dozen where the position is directly elected by the public. That arrangement is a direct legacy of the state’s consumer advocacy movement; in 1988, voters furious over soaring automobile insurance rates passed a ballot measure that transformed the role from an appointed office into an elected one.
In practice, however, it is a post few would envy. The commissioner possesses the authority to approve or deny rate increases, police industry compliance with state regulations, and oversee the FAIR Plan. Yet the commissioner holds limited direct power to compel private insurers to write policies in dangerous regions or to unilaterally reduce the underlying wildfire risks facing remote properties.
"The insurance commissioner has a lot of power and authority himself or herself that they should use, but the insurance commissioner alone cannot address these challenges," noted Dave Jones, who served as state insurance commissioner from 2011 to 2019.
Outgoing commissioner Ricardo Lara held the office through nearly the entirety of the market’s wildfire-induced collapse. Lara’s tenure was marked by shifting strategies, oscillating between attempts to collaborate closely with major insurance carriers and efforts to crack down on them, occasionally risking insurer flight from the state. After initially pledging to reject campaign donations from the insurance industry, he later accepted contributions, a move that drew intense public scrutiny when subsequent rate hikes stalled, prompting companies like State Farm to shed additional policies.
Lara’s signature effort to stabilize the market involved striking a compromise agreement with insurance providers. He permitted companies to pass the costs of reinsurance—effectively insurance purchased by insurers—directly onto consumers, while also allowing them to adopt forward-looking catastrophe models to project future disaster risks, a practice already standard in most other states. In exchange, insurers committed to writing a greater volume of policies in high-risk fire zones.
However, the arrangement was criticized for containing loopholes that allowed insurers to meet their underwriting quotas without actually returning to the most hazardous areas. Meanwhile, the state FAIR Plan continued absorbing a growing share of the market in the wake of the 2025 Los Angeles fires. In an interview with the New York Times, Lara asserted that the insurance industry had "bullied" him. His office declined subsequent interview requests, and representatives for the FAIR Plan did not respond to inquiries.
Two Visions for Reform
Despite the entrenched nature of the crisis, a dozen candidates entered the primary race to succeed Lara. The crowded field featured four Democrats, five Republicans, and two independents, most of whom lacked the funding required to run a full statewide campaign amid sparse public polling.
The primary results surprised even the political campaigns. The top two spots in the primary went to Democrats. Claiming first place with roughly 27 percent of the vote was Jane Kim, a former San Francisco supervisor and ally of Bernie Sanders who campaigned on a platform proposing a government-run single-payer program for disaster insurance. Finishing second was Ben Allen, the state senator representing Pacific Palisades and one of the legislature’s foremost policy experts on insurance.
Allen and Kim share several common goals. Both advocate for simplifying standard insurance policies and forcing companies to disclose their spending and corporate investments in fossil funds. Both support expanding the operational scope of the FAIR Plan to provide automatic coverage for smoke and secondary damage—a reform that would have spared McIntyre months of administrative limbo. Additionally, both candidates have pledged to crack down on insurers that deliberately delay or nitpick claim payouts following major disasters, and both have refused campaign contributions from the insurance industry.
The core divergence between the candidates centers on how to transition homeowners off the FAIR Plan and stabilize the broader market. Allen contends that if the state permits insurers to charge economically rational rates for high-risk homes, invests aggressively in property hardening, and relies on transparent data to measure wildfire risk, private carriers can be enticed back, ultimately restoring a functional market.
Kim, conversely, advocates for discarding the private market model entirely. She proposes establishing a universal, state-run public insurance program covering all homes against all disasters, effectively replacing private wildfire coverage and phasing out the FAIR Plan. Rather than generating profits for corporate investors, this public program would channel excess revenues directly into funding community-wide wildfire resilience and home retrofits. Under her proposal, private insurers could continue writing policies for standard perils like burglary, but the state government would collect all wildfire premiums and manage all payouts—a structural model inspired by existing programs in countries like France and New Zealand.
This philosophical clash exposes a deeper debate over whether private capital markets remain capable of protecting communities against the mounting threats of climate change.
Allen decided to run for commissioner after the Palisades Fire scorched a substantial portion of his legislative district, plunging many of his constituents and friends into displacement and insurance disputes. Even prior to the disaster, he spent years chairing legislative committees focused on insurance, energy, and wildfire mitigation, positioning himself as uniquely experienced to tackle the job.
"I think we need someone in this office who really understands climate science, who understands the markets, who understands the legislature," Allen said. He noted that experiencing the Palisades Fire firsthand provided a distinct perspective—listening to friends itemize destroyed furniture and observing pollution washing into the Santa Monica coastal waters.
Rather than leveraging the commissioner’s office to pursue a massive legislative overhaul like Kim’s public fund, Allen emphasizes the concept of poder de convocatoria, or convening power. He aims to bring state agencies and insurance executives to the table to negotiate concrete risk-reduction strategies and coax private providers back into the market. He recently secured passage of a bill providing low-level, low-interest loans to homeowners seeking to fire-harden their properties, outlining a grand bargain that would accelerate rate approval decisions in exchange for stricter enforcement against companies that unreasonably deny claims.
Kim’s progressive proposals have clearly struck a chord with voters. She outperformed Allen in the primary across numerous counties, including Allen’s home county of Los Angeles, and performed surprisingly well in several rural and politically conservative regions.
"There’s this sense of immense unfairness, and once we articulate the problem, and then on top of that, actually propose big policy ideas, I think that that resonates," Kim said during a campaign event in San Francisco.
Industry veterans and former regulators remain skeptical of a government-run takeover. Dave Jones argued that Kim’s model suffers from fundamental flaws, noting that promises to keep public insurance affordable could result in artificially suppressed rates for luxury properties in high-risk areas. Furthermore, he noted that California regulations require insurers to maintain tens of billions of dollars in liquid reserves to cover catastrophic loss events—capital that a public fund would struggle to secure given the state’s already strained budget.
"Not only does she not come clean as to where the money’s going to come from, if her thought is that it’s going to come from the general fund of the state of California, good luck," Jones said, pointing out that New Zealand’s model is significantly smaller and excludes fire coverage entirely. Allen similarly dismissed the proposal as politically expedient rhetoric that would ultimately leave taxpayers holding the bill if the public fund suffered heavy losses.
Recognizing potential legislative resistance to a full single-payer overhaul, Kim has floated a compromise: transforming the existing FAIR Plan into a quasi-public resilience engine. By leveraging the pool of capital collected from major insurers, the commissioner could mandate additional fees dedicated specifically to funding property hardening for FAIR Plan policyholders.
"What the insurance industry does is that they price risk, but they don’t actually address it," Kim argued, asserting that private corporations should not retain exclusive control over public safety in an era of intensifying climate disasters.
Allen counters that while the industry has historically failed to proactively reduce California’s monumental fire risk, private companies can be compelled to play a constructive role through rigorous regulatory engagement.
The Monumental Challenge of Risk Reduction
Regardless of which regulatory path is pursued, the underlying physical reality remains exceedingly difficult: reducing wildfire risk across millions of established properties is an immense logistical challenge.
Consider the experience of Tony Byers, a retired electric utility worker and longtime resident of Placerville, a historic mining community nestled in the forested foothills east of Sacramento. After years of coverage with AAA, his policy was canceled following a 2022 fire that burned a nearby section of the Sierra Nevada. State Farm subsequently issued a quote before rejecting him based on an erroneous claim that his home lacked proximity to a fire hydrant. Byers eventually secured a policy with the online insurer Lemonade, clearing flammable trees from his property at the company’s request, only to be informed last year that Lemonade was withdrawing from California entirely.
Relegated to the FAIR Plan, Byers now pays $3,400 annually for fire coverage alone—triple his previous rates. Residing at the end of a narrow mountain road, he estimates that qualifying for a private policy would require spending tens of thousands of dollars on property retrofits, an expense far beyond his fixed retiree budget.
Conversely, homeowners with substantial financial resources can bypass the standard market entirely by purchasing elite surplus lines coverage. Kevin Roberts, a retired golf course owner living in the affluent Huntington Palisades neighborhood near the recent burn scar, was unable to secure standard fire insurance from major carriers. Instead, he utilized a boutique broker to purchase a surplus lines policy through Chubb. The policy costs upwards of $30,000 a year and operates outside standard state rate regulations, but it delivered a $2.65 million payout for smoke damage following the Palisades fire. The state’s surplus lines market has doubled over the past four years, growing to approximately 1.3 million policies as wealthy homeowners seek out unregulated alternatives.
"You’ll pay more, but if you need them, they’ll deliver," Roberts said.
Scaling risk reduction efforts across California represents one of the most complex climate adaptation hurdles in the United States. The difficulty lies not merely in securing financial subsidies for vulnerable homeowners, but in determining how to physically retrofit millions of aging, flammable structures built across a century of sprawling development.
In Lake County, north of San Francisco, poverty-fighting nonprofit North Coast Opportunities became the first recipient of a $117 million state grant program designed to harden entire communities against wildfire. The organization targeted Kelseyville, a densely clustered neighborhood situated against a windy mountain ridge where roughly 85 percent of the surrounding land has burned since 2000. Insurers have largely abandoned the area, pushing residents onto the FAIR Plan or leaving them entirely uninsured.
Utilizing state grant funding, the nonprofit provides participating households with approximately $70,000 to execute targeted structural retrofits—clearing defensible space, replacing vinyl siding with fiber cement, and removing flammable wooden decks. Despite the modest appearance of the finished homes, the retrofits require meticulous coordination. Contractors must frequently redo substandard construction work, local hardware suppliers must source specialized fireproof materials, and many residents remain resistant to participating.
"What creates an insurable community is for the whole community to have buy-in," said Deanna Fernweh, program manager for the initiative. "It’s changing the mentality, because they’re like, ‘Well, we’ve always done it this way.’"
While some insurers have expressed curiosity about the community-level mitigation work, carriers increasingly push for entire neighborhoods to meet stringent wildfire resilience standards before returning. The Kelseyville project, while impactful, touches only about 300 out of 1,200 eligible homes in the immediate area, illustrating the vast gap between current grant funding and the scale of the statewide vulnerability.
"A home is only as strong as the weakest link," said Steve Hawks, director of wildfire programs at the Insurance Institute for Business & Home Safety. "If you leave a weak link on the table, a fire of [significant] magnitude can exploit any vulnerability."
Retrofitting older housing stock to withstand intense wildfires can often cost multiple times more than constructing a new resilient home. Replicating those modifications across millions of properties in California’s high-risk zones carries a multi-billion-dollar price tag, forcing both political candidates to confront the central reality of the crisis: risk does not simply vanish; it must be allocated and paid for.
As Holly Sacks, director of underwriting for California-based Mercury Insurance, noted, the market stabilization process remains in its early stages. While Mercury continues writing policies in fire-affected communities like Paradise and Altadena, it does so exclusively for properties that meet rigorous hardening standards.
The structural repair of California’s insurance market remains a daunting undertaking, but the underlying stakes extend far beyond financial accounting. The availability of insurance underpins the modern economy, representing a social compact wherein a community pools its resources to protect its members against unforeseen catastrophes. Preserving that shared guarantee remains one of the defining challenges of a warming world.